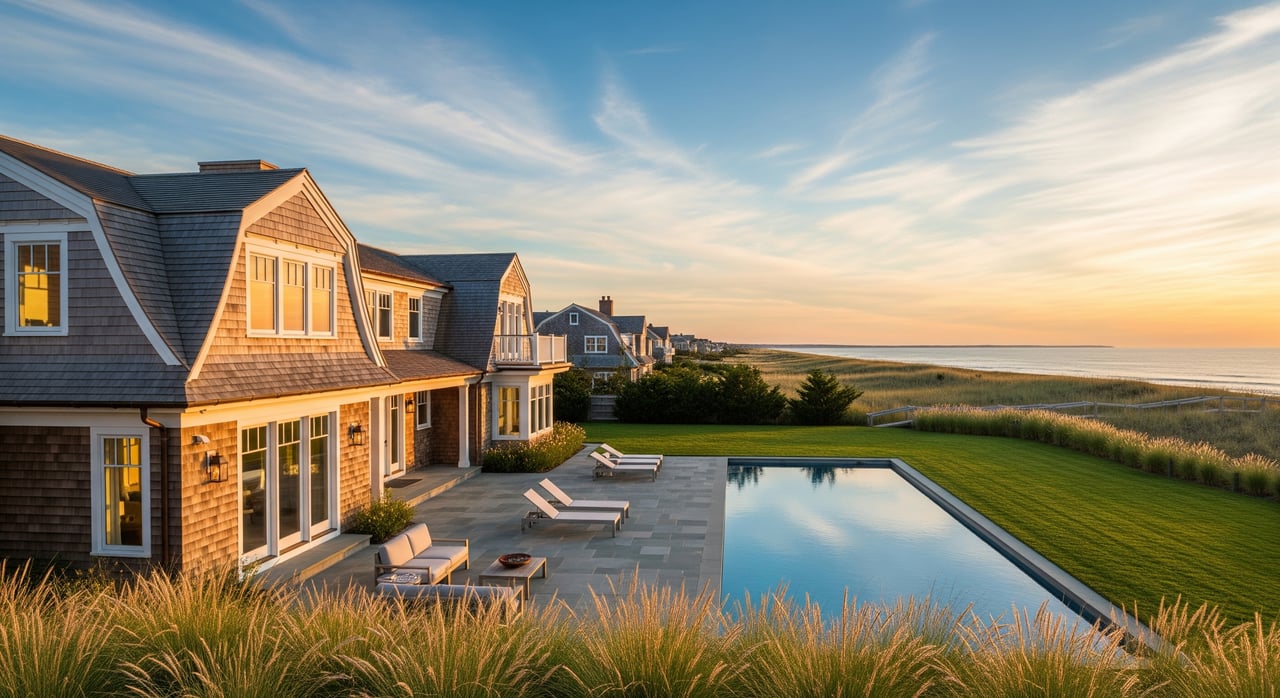
Thinking about Sagaponack but wondering how it stacks up against the U.S. housing market? You’re not alone. Sagaponack is a small, coastal village in the Hamptons where luxury and second homes dominate, so the numbers behave differently than national averages. In this guide, you’ll learn what drives those differences, how to read local data without getting misled, and how to time your move. Let’s dive in.
Why Sagaponack diverges from U.S. averages
Luxury and second‑home mix
Sagaponack has a high concentration of luxury properties and second homes. That mix elevates price levels and changes what “typical” looks like. Many buyers are purchasing for lifestyle and long‑term value, not just commuter convenience.
Demand here often tracks wealth trends and stock markets more than local employment. That can decouple Sagaponack from broader national cycles that hinge on job growth and affordability.
Small sample size swings
Sagaponack is small. A few high‑value sales can move the median price a lot. Month‑to‑month charts can look volatile even when the underlying trend is steady. Treat short time frames with caution and focus on multi‑quarter or multi‑year views.
This is also why segmenting by price band is essential. A shift in the share of sales over $5 million can create a “spike” that is really just a composition change.
Seasonality patterns
Spring brings new listings as sellers position for summer activity. Closings often cluster in late spring and summer. Off‑season, days on market can stretch and inventory can look higher.
National data rarely shows this level of seasonality. Here, timing choices have outsized effects on exposure, showings, and outcomes.
Cash buyers and rates
Second‑home and luxury markets tend to have a higher share of cash purchases. That softens the direct impact of mortgage rate changes. Rates still matter for financed buyers and overall sentiment, but the link between national rate moves and local pricing is weaker than in primary‑residence markets.
Coastal risk and insurance
Flood zones, storm surge exposure, and shoreline dynamics add real costs and due‑diligence steps. Insurance availability and premiums can influence buyer demand and value, especially for waterfront or low‑lying parcels. Pay attention to current FEMA flood maps and recent carrier changes when evaluating risk.
Taxes and carrying costs
Property taxes, homeowner insurance, flood coverage, utilities, and maintenance are material here. These carrying costs are often higher than national averages and should be included in your budget and pricing strategy. For some buyers, favorable financing or trust structures help with planning, but the ongoing costs remain a key factor.
How to read the market data
Prices and price bands
Look at median and average prices, but always check the share of sales in key bands such as above $2 million or above $5 million. Composition can change quickly in a small market and can make a single metric misleading.
A price‑band view helps you see whether the entry tier or the ultra‑luxury tier is driving recent movement.
Price per square foot
Price per square foot helps normalize for different home sizes. In Sagaponack, lot value, view corridors, and privacy premiums can push per‑square‑foot figures above what the house size alone suggests. Compare like‑for‑like when possible.
Use per‑square‑foot trends to sense direction, then ground decisions with a property‑specific valuation that reflects land, improvements, and redevelopment potential.
Months of inventory and supply
Months of inventory (MOI) shows market balance. Expect lower MOI in spring and early summer when demand peaks. MOI can rise in late summer and fall as new supply meets buyers who have already transacted.
Because Sagaponack is small, a handful of listings can shift MOI sharply. Use year‑over‑year comparisons for the same month to understand true seasonality.
New listings and sales volume
Listing activity is concentrated in late winter through spring. Closed sales often follow with a lag. A slow January does not say much about the year. Watch the late winter listing pulse and how quickly top properties go under contract.
If sales volume thins while high‑quality homes still trade, that can signal a selective, opportunity‑driven market rather than broad weakness.
Days on market and negotiation
Days on market (DOM) often stretches in the off‑season. The list‑to‑sale price ratio can also vary by price tier, with higher‑end properties sometimes showing wider negotiation ranges due to unique features.
For sellers, proper pricing and launch timing matter more here than in many U.S. markets. For buyers, patience and preparation can unlock value, especially off‑season.
Property types and waterfront
Waterfront and oceanfront properties carry distinct premiums and risks. Lot size, dune structure, and regulatory history can matter as much as finishes. Vacant land and teardown opportunities follow a different logic, often tied to zoning limits and replacement cost.
Segment your analysis by property type. It will clarify trends and help you avoid apples‑to‑oranges comparisons.
Timing your move in Sagaponack
Best time to list
If you want peak exposure, prepare in winter and hit the market in early spring. Buyer traffic rises ahead of summer, when in‑person visits are easiest and demand is strongest.
Off‑season listings can still succeed with the right pricing and marketing. They just require sharper targeting and patience.
Best time to buy
If you value choice, spring typically offers the widest selection. If you value negotiation room, late summer into fall can be attractive as the seasonal rush fades.
Your best timing always depends on your segment. For a unique property, move when it becomes available and be ready to act.
Off‑season strategy
Off‑season can be a window for due diligence. You can assess drainage, wind exposure, and access without summer crowds. Contractors and inspectors can also be more available.
If you plan to launch a listing off‑season, ensure professional media, staging, and a targeted outreach plan so you are top of mind when spring buyers organize their tours.
Risk, due diligence, and value
Flood zones and insurance
Confirm the property’s flood zone and base flood elevation against current maps. Check recent insurance quotes and any lender requirements. Waterfront premiums, storm deductibles, and coverage limits can vary by carrier and by elevation.
Ask for prior claims history when available, and factor mitigation options like elevation certificates, shutters, or drainage upgrades into your cost and risk calculus.
Property taxes and assessments
Review assessed value, exemptions, and recent tax bills. In Sagaponack and the Town of Southampton, tax structures and village assessments can add up. Align your valuation with likely future assessments, not only current bills.
If you are selling, have clear documentation on taxes, utilities, and maintenance to help buyers model carrying costs with confidence.
Zoning and rebuild potential
Setbacks, height limits, wetlands, and coastal regulations shape what you can build or expand. Redevelopment potential often drives value as much as current finishes.
Pull permits and review any variances or coastal approvals on file. Understanding what is possible on the lot can prevent surprises and support stronger pricing.
Climate and regulatory outlook
Plan on continued attention to sea‑level projections, shoreline management, and insurance market changes. Values remain strong for well‑sited, well‑mitigated properties, but the market is more sensitive to new information. Stay current on local guidance and disclosures.
What this means for buyers
- Build a total cost view. Include property taxes, homeowner insurance, and any flood coverage in your budget.
- Get prepped for speed. Cash or verified funds help in a selective, high‑end market. If financing, have your file ready.
- Focus on the lot. Elevation, setbacks, and privacy hold lasting value. Interiors can be updated.
- Use price bands, not just medians. Compare your target tier with recent trades to judge value.
- Plan for seasonality. See homes in different months if you can. Off‑season visits can reveal practical details.
- Prioritize due diligence. Order surveys, elevation certificates, and permit histories early in the process.
What this means for sellers
- Time the launch. Early spring maximizes in‑person traffic. Off‑season can work with disciplined pricing and targeted marketing.
- Price with precision. Anchor to recent trades in your tier and adjust for unique features. Avoid chasing headline medians.
- Lead with the land. Present lot size, setting, and privacy benefits clearly.
- Remove friction. Prepare disclosures, tax and utility summaries, and recent insurance information.
- Elevate presentation. Professional media, staging, and a clear narrative reduce days on market.
- Protect privacy. Control showings and pre‑qualify interest when appropriate.
National comparison at a glance
- Price level: Sagaponack sits far above national medians due to its luxury mix.
- Volatility: Small sample sizes create sharper swings in monthly medians and MOI than national charts.
- Seasonality: Spring and summer dominate; national seasonality is milder.
- Cash share: Higher share of cash reduces sensitivity to mortgage rate changes.
- Inventory: Supply ebbs and flows with the season more than with national construction trends.
- Buyer geography: Out‑of‑area buyers are common, changing the role of local employment metrics.
Work with a local advisor
A strong result here requires more than watching national headlines. You need hyperlocal pricing, a property‑specific due‑diligence plan, and a launch strategy that fits Sagaponack’s seasonal rhythm. You also need quiet, disciplined negotiation and marketing that reaches the right buyers quickly.
If you are weighing a purchase or planning a sale, connect with a trusted local team that blends discretion with modern marketing systems. For confidential guidance tailored to your goals, reach out to Dennis Saglam.
FAQs
How do Sagaponack home prices compare to U.S. prices?
- Prices in Sagaponack are typically much higher than national medians due to the luxury and second‑home mix, so compare by price band and property type for accuracy.
How seasonal is Sagaponack compared to the national market?
- Listing and closing activity are concentrated in spring and summer, while national markets usually show a milder seasonal pattern.
How sensitive is Sagaponack to mortgage rate changes?
- The higher share of cash buyers reduces direct rate sensitivity, though financing costs still influence some segments and overall sentiment.
What should buyers know about flood risk and insurance in Sagaponack?
- Confirm flood zones, elevation, and recent insurance quotes early, since premiums and coverage vary by property location and features.
How do taxes and carrying costs in Sagaponack compare nationally?
- Expect higher carrying costs than national averages; budget for property taxes, homeowner insurance, and any flood coverage from the start.
Are most Sagaponack homes primary residences or second homes?
- Many properties function as second homes or seasonal residences, which shapes demand patterns and the importance of lifestyle features.
